Bottom line: there are basically two things that matter in tenant screening, and they matter a whole lot: 1) Eviction and landlord collections history; and 2) Credit score.
That second one actually surprises me, and it contradicts my thoughts I had posted on LinkedIn. Internally at my own PM company, we’ve just never seen a correlation between credit score and default rate, but I have some thoughts on why that might be below. So let’s do the deep dive!
The High Cost of Getting it Wrong
TransUnion found that the average cost for a landlord nationwide of selecting a bad tenant who ends up defaulting is $3,500. That’s actually lower than I would expect, but I think my view has been skewed post-Covid by how terribly the counties in the heart of Metro Atlanta have been with eviction timelines. For those in places with quick evictions still like Arizona and Florida, those numbers are probably pretty close to accurate if you exclude the cost of re-renting.
PMAssist Industry Insights is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.
Either way, it’s a big cost. And that’s why churn of owner clients is so high following an eviction. Churn of owners is always correlated with churn of residents, but even more so when resident churn is from an eviction or skip.
Another number that is interesting came from Experian, stating that 7% of all leases end in default. That’s the first time I’ve seen reliable data on that metric. Historically, the rate of eviction nationwide hovers right around 5%, so that means the additional 2% is coming from tenants just skipping out. We’ve generally found over the years that professionally managed properties have an eviction rate of about half the national average, so that 7% is probably closer to 3.5% when using a professional PM. Still a sizable risk when the cost is $3,500 when you get it wrong.
Rental History is King
My initial belief that credit score isn’t the most important factor was correct, I was just wrong that it doesn’t matter much at all. What matters most is rental history, specifically evictions and landlord debt. Both TransUnion and Experian found the same basic results, but Experian had the much bigger dataset with 755,000 residents (a truly massive dataset for statistical analysis), so we’ll use their numbers so we can be the most accurate:
Residents with 1 prior rental debt had a 23.2% default rate
Residents with 2 or more rental debts had a 35.2% default rate
Residents with a clean rental history had only a 5.96% default rate
Really think about that. This means that a resident with even one hit on their background check for landlord debt has nearly a FOUR FOLD increase in their likelihood of being evicted or skipping out.
Property Meld has spent over a decade capturing millions of maintenance data points to power our intelligent automation, MAX™. Now, we’re taking it a step further with MAX On-Call.
It’s more than after-hours coverage. It is maintenance intake reimagined.
Traditional call centers often create more problems than they solve. Emergencies are misclassified, leading to after hour rates when it’s not needed. Work orders arrive hours later, missing crucial details.
MAX On Call changes that.
Powered by 10+ years of maintenance intelligence, MAX handles intake 24/7, triages accurately, and only escalates true emergencies.
Every call is documented with complete information, and work orders are generated instantly. And that’s just scratching the surface of what MAX can deliver.
The result? Lower costs, less stress on your team, and residents who feel cared for.
With this data in mind, there is only one responsible thing any property manager can do for their clients: have a strict prohibition on renting to anyone with even a single dollar still owed to a prior landlord. This should be a hard limit. It’s not something you make exceptions to if other stuff looks good or if their income is really high. It doesn’t matter how good their job is or how well their last landlord speaks of them. Again, a 400% higher default rate. You are literally negligent to rent to someone with prior landlord debt. Do not play around with this.
Credit Scores Matter, But Don’t Tell a Full Story
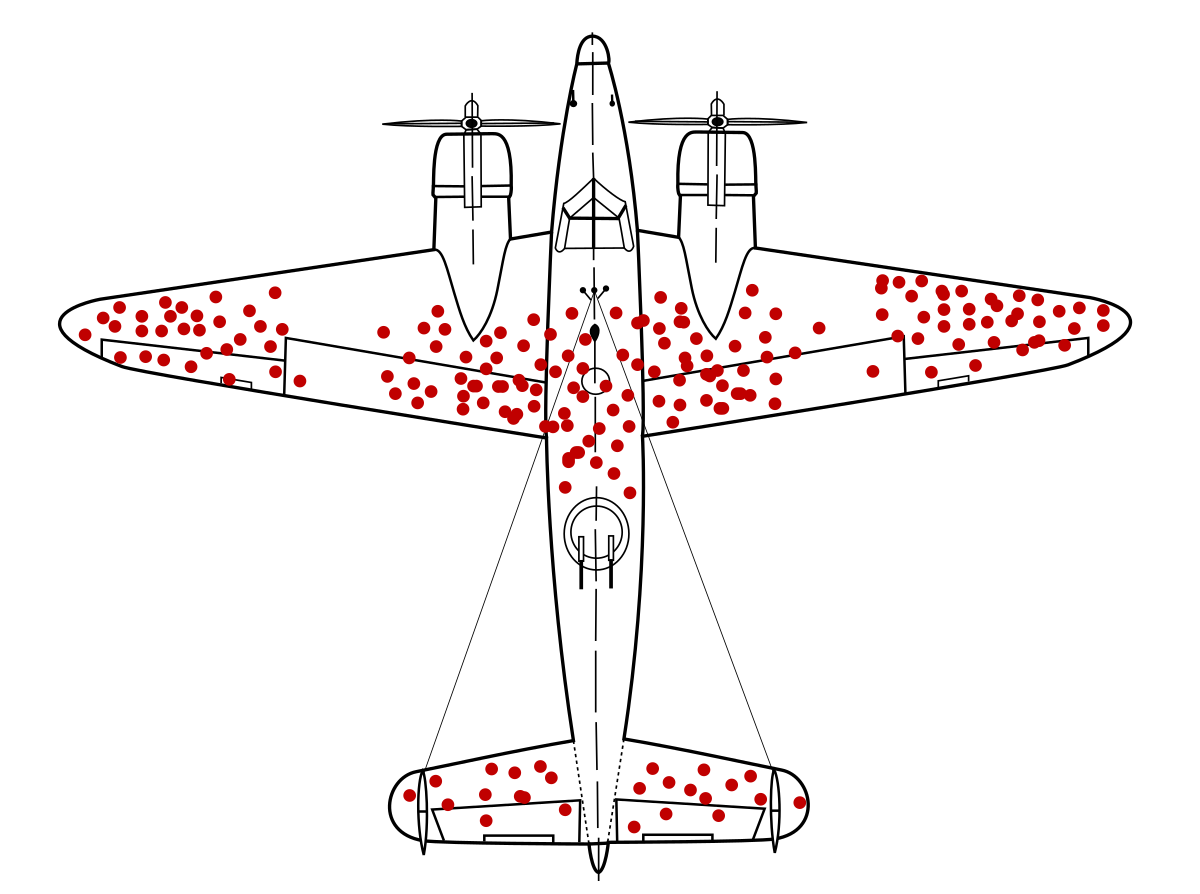
If you look at my own company’s internal data from years of tracking this stuff, you’d think that credit score is irrelevant. There is literally zero statistically meaningful difference in our eviction rate between a 750 credit score resident and a 500 credit score resident. So when I posted my initial thoughts on LinkedIn last week, I said that credit score doesn’t matter. But I fell into a logical error here called “survivorship bias.” You might have seen the below graphic elsewhere at some point, because it’s a common illustration of this logical error:
This graphic is a representation of how aircraft returning from battle in World War II would be damaged. You’ll notice lots of damage to most areas of the aircraft, but very little to the engines, fuel tanks (which are in the mid-wing area), and crew compartment/cockpit. Why? Because if an airplane survived well enough to return to the airfield or carrier, it wasn’t hit in those areas. If an engine gets hit, the plane is likely going down, so you’d never get a returning plane with damage there.
Statistician Abraham Wald correctly took this survivorship bias into account during the war when he was trying to figure out how to reduce aircraft losses, and he recommended additional armor to the areas showing the least damage. His work became one of the groundbreaking studies in the early field of operational research.
So how did I fail to see what Wald did in my own resident default data? Well, I’m only looking at data from people we approved and signed a lease with. If an applicant was denied, or if they never moved forward with a lease, they don’t show up in my dataset, unlike the Experian dataset which included all applicants.
This is an important distinction, because although my own company doesn’t deny applicants based solely on credit score, we DO charge higher deposits and risk mitigation fees on that basis. And, of course, we also straight up deny anyone who owes prior landlord debt, regardless of how good their credit is. As a result, our dataset is limited. When we approve people with lower credit scores, we are only approving people who have zero prior history of landlord debt, and they are also having to come up with more money to move in. This means that only the low credit residents who have enough cash to pay bigger deposits and higher monthly fees are moving forward with signing leases. So we’ve basically filtered out the low credit people who would have caused us problems using other criteria. Only the residents with lower credit scores who will be good tenants are making it through our filters. I failed to take this into account with my prior comments and views on credit scores.
However, this still reinforces the same general idea: credit scores can’t be used alone as a screening methodology. As one of the studies puts it:
“Applicants may demonstrate strong rent payment history even if their traditional credit profile reflects delinquencies on other types of debt.”
Traditional credit scores are designed to predict general financial behavior. Think credit card payments, utility bills, auto loans, etc. But how well someone does at paying a credit card bill may have no correlation whatsoever to how well someone pays their rent. Some people just view different kinds of debts with different priorities.
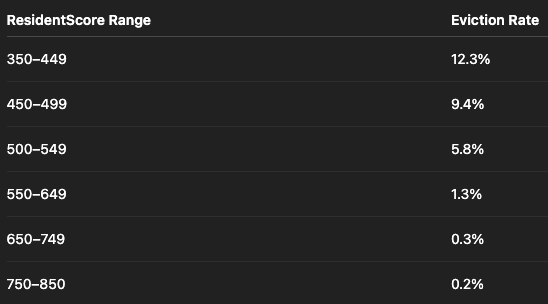
So, we need to take credit score into account, but if you’re just denying everyone with a lower score, you’re screening out a lot of great tenants. One way to correct for this is to use something like TransUnion’s ResidentScore, which factors in landlord debt more heavily and attempts to correct for these differences in credit profiles. Here is what the eviction rate is based on ResidentScore:
Honestly, from 550-850, there isn’t enough difference to matter here. But under that, the eviction rate is meaningfully different. From 550 to 500, the eviction rate increases from 1-in-100 to 1-in-17.
The other way to handle this if you don’t use TransUnion’s ResidentScore is to do as I’ve been doing: increase the cash required to rent for those with lower credit scores. Bump up the deposits and fees, and the people who would have defaulted weed themselves out, creating the appearance of credit not mattering as I previously said.
What About No Credit?
For those of us who own property and businesses, it’s hard to imagine someone not having a credit score in 2025. How do these people even exist in a modern society? But not only do they exist, they exist in enormous numbers. Experian says that over 64 million Americans fall into this category. That’s 1 out of every 5 adults who have no credit score whatsoever.
Not only does it make little sense to immediately screen out 20% of the entire tenant population nationwide from qualifying to rent from you, it simply isn’t politically sustainable. Eventually lawmakers will step in to stop you from doing so, because they aren’t going to let 20% of their constituents go without good housing. So you need to find a better way of screening no-credit individuals instead of just denying them outright, because if we all keep doing that, politicians will just take away our ability to do so when they figure out what’s happening. This is especially true when you dig deeper into the dataset and realize that these no-credit individuals largely come from groups that dominate the voting block for the Democratic Party: young people, immigrants, and low-income households. You might have noticed that one of those categories, immigrants, is a protected class under the Federal Fair Housing Act. Have you heard of disparate impact? If not, look it up. Republicans may rule the roost right now, but that will change at some point, because it always changes. And when Democrats come into office again, if you are systematically screening out 40% of their voting block from having housing, they are going to take action. That’s the biggest special interest group imaginable.
That said, we can’t just ignore the fact that people have no credit. It does tell a meaningful story. The Experian dataset shows that even those no-credit individuals with positive rental history have a 9% default rate, which is a statistically meaningful difference from the 5.96% default rate of the overall population of people with positive rental history. So we do need to be more diligent in screening these individuals to make sure we’re only taking the ones who will be able to meet their financial obligations.
The way to do this is to treat these applicants as approvable, but with additional conditions. Charge a bigger deposit and risk mitigation fees (in markets that allow it). If you offer an in-house security deposit alternative, the fees should be higher for these applicants. Until they establish credit history (which you should help them do with your RBP), they need to be treated as a greater risk, but not as someone completely un-approvable.
Final Thoughts
The future of property management is data-driven. Both of my articles this week focused on data, first related to maintenance, and today related to tenant screening. This isn’t the old days, and we can’t keep shooting from the hip using our gut instincts. Where data is available, we need to be using it. Our industry has matured and grown exponentially over the past couple of decades. If you are still making decisions from your gut, you are going to be left in the dust of your competitors who are using statistical data to produce better results for themselves and their landlord clients.
When it comes to tenant screening, that means we need to be paying a lot more attention to rental history than we are to credit scores, but we still need to be factoring in credit to a certain extent. Layering on top of that higher security deposits and fees for less creditworthy residents will improve your outcomes even more.
This week, Second Nature revealed the industry’s first Resident Experience Platform (RXP) - giving property managers the ability to deliver modern, personalized onboarding experiences that residents understand and appreciate.
RXP transforms the move-in process from stress to success - guiding residents through lease terms, move-in tasks, and benefits in a clear, mobile-first format. It’s built to save property managers countless hours while creating happier residents who stay longer, pay on time, and renew more often.
I would also say that my view hasn’t changed from my LinkedIn post that the most important factor is still rent-to-income ratio. Sadly, these reports from Experian and TransUnion did not even address this factor at all. That’s not surprising, since they don’t score people on that basis in their business model, so they had no incentive to highlight it. But I would point out that this data is incredibly hard to come by. I had AI do some deep research trying to find any reliable data from any sources out there on how income correlates to lease default rates, and the data basically does not exist. No academic institutions or businesses have commissioned studies on this topic, unfortunately. Internally, I am going to start tracking it along with our tracking on credit scores and default rates, and I’d encourage you to do the same. I strongly suspect that my instincts will be borne out by the data, but we won’t know for certain until we have a large enough dataset.
In the meantime, focus primarily on rental history, then consider credit secondarily and find a way to fit in people who have no credit at all. Filter out on the front-end by rent-to-income ratio, probably requiring 3x for your standard approval and higher deposits and fees if you allow below that. Hopefully in a couple of years we’ll have enough hard data to be able to put together a sizable dataset to give meaningful predictive value based on rent-to-income ratio.
Open to Work
Are you an experienced PM industry employee looking for work? Or are you a PM company or vendor seeking the best talent? Send me your info and I’ll feature it here!
And starting this week, we’re featuring a Remote Team Member every week available through VPM Solutions. First one below! Click on the image to get more info.
Newsletter Stats
Here are our statistics for the last 30 days (Substack brought back impressions data!):
We always have some available ad slots open for industry vendors, and we offer discounts if a slot is still open within the next four weeks. Sign up for an ad or ad package here. Pricing and ad details can also be found at that link.
Debate Me
Disagree with my take here? Have a different perspective? There’s nothing I love more than a good debate or even just an intelligent conversation. If you’d like to jump on a podcast recording with me to discuss this topic, please let me know!
PMAssist Industry Insights is a reader-supported publication. To receive new posts and support my work, consider becoming a free or paid subscriber.
Yep. Bad rental debt = declined. Bad credit = let's talk about it. We can usually make them an offer for the house with increased Sec Dep and Credit Risk Fee.




Yep. Bad rental debt = declined. Bad credit = let's talk about it. We can usually make them an offer for the house with increased Sec Dep and Credit Risk Fee.